

- Karnataka ranks next to TN in south for groundwater-recharge water bodies
- AAP Delhi chief Saurabh Bharadwaj calls emergency meeting, says ‘something big’ being planned by Centre
- Congress-NDA row over video clip of interruption to FM Sitharaman's speech in Andhra Pradesh
- Government orders postings of Divisional Development Officers
- Dasara special puja tickets to be issued from Oct 5
- Show-cause notices issued to 26 APCC members
- Narayana launches development works worth Rs 2.80 crore
- Govt fully prepared to conduct local body elections
Eight-week market slide raises caution ahead of RBI policy
In Short
Investors track crude, inflation, rupee and foreign flows as volatility stays elevated
Share :
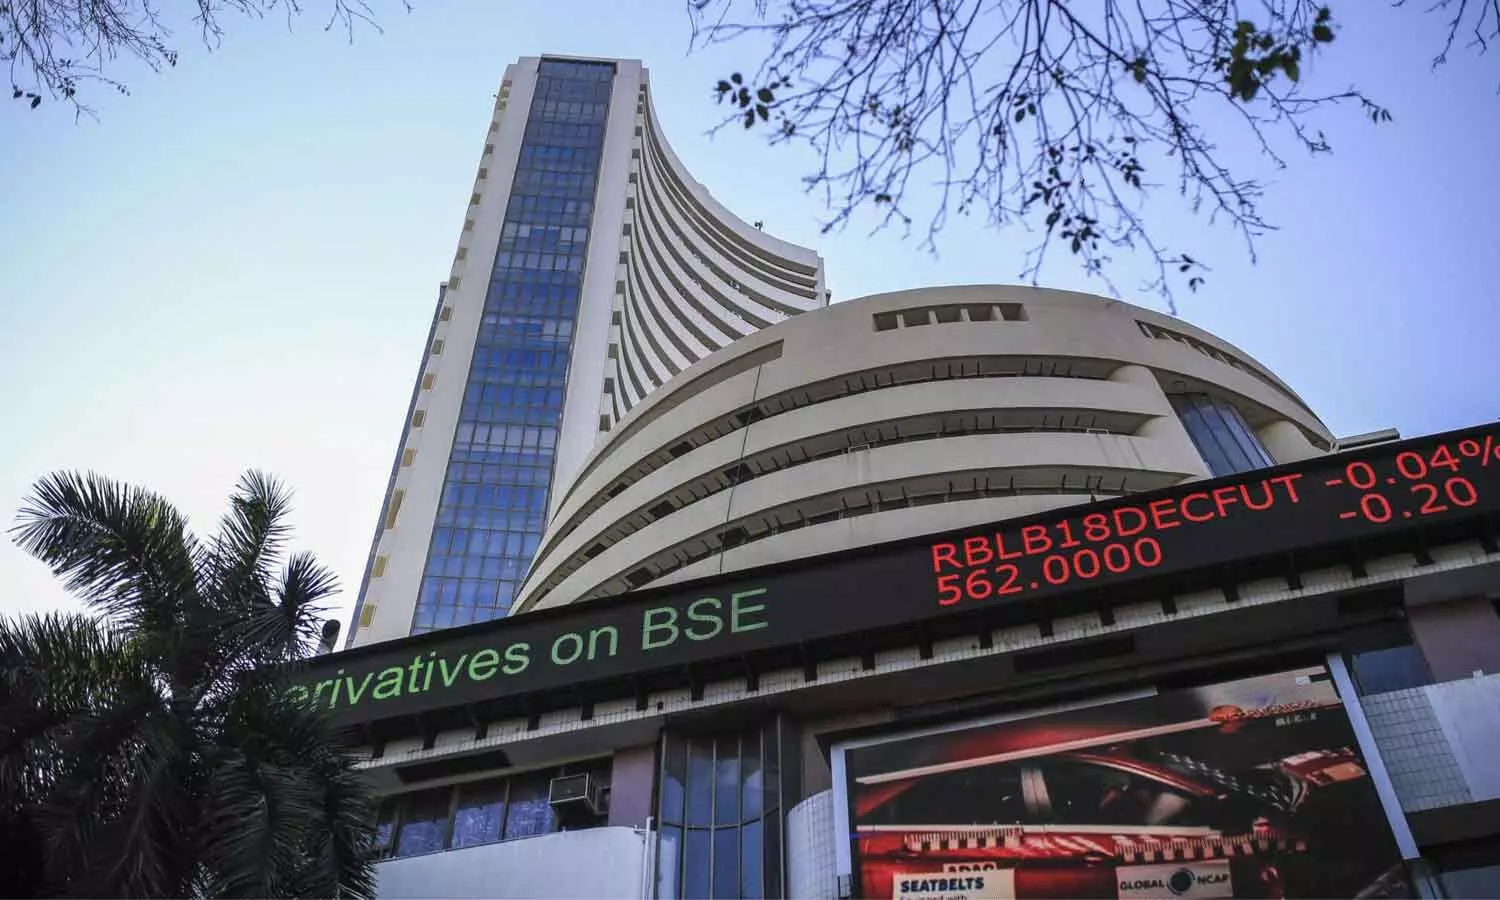
Eight-week market slide raises caution ahead of RBI policy
The persistent energy shock also stalled the multi-year global disinflation process, while higher diesel, jet fuel and natural gas prices put pressure on household savings and trade bal-ances in energy-importing countries
Spooked by elevated international crude oil prices amid renewed tensions in the Middle East, rising global bond yields, persistent foreign fund outflows and a weakening rupee; equity mar-kets extended their losing streak to the eighth consecutive week, marking the longest weekly de-cline in 25 years and surpassing the streaks seen during the 2020 Covid-19 crash and the 2008 global financial crisis.
For the week, the Sensex plunged 1,986.04 points, or 2.68 per cent, to 71,909.70, while the Nifty tumbled 718.55 points, or 3.10 per cent, to 22,421.95. Volatility expanded sharply alongside the decline in the benchmark indices. The Nifty Midcap 100 index declined 3.5 per cent and the Nifty Smallcap 100 index extended its losing streak for the fourth consecutive week, declining 3.3 per cent. FIIs accelerated their selling during the week, extending their selling streak to the sixth consecutive week, offloading equities worth Rs34,966.07 crore. Meanwhile, DIIs continued to provide support, purchasing equities worth Rs33,455.30 crore during the week.
The market selloff eroded nearly Rs15 lakh crore from the combined market value of BSE-listed companies during the week. After remaining rangebound during the first three days, the Indian rupee came under pressure on Thursday and moved closer to its record low of 96.96 to close at 96.32. During the week, the rupee traded in a range of 95.74–96.32 against the greenback.
India Manufacturing PMI rose to 55.1 in September from 52.8 in August, the strongest improve-ment in the health of the sector for seven months. However, August CPI inflation increased to 4.82 per cent, moving further above the RBI’s 4 per cent target and adding to concerns over the inflation outlook. In the last meeting, the RBI has retained the repo rate at 5.25 per cent with a neutral stance and projected FY27 GDP growth at 6.7 per cent.
The RBI Monetary Policy Committee is scheduled to meet from October 5–7, with the policy de-cision due on October 7. This event may keep interest-rate-sensitive pockets and the broader market somewhat cautious ahead of the announcement and could contribute to elevated intra-day volatility around the policy outcome. Closely track the RBI’s assessment of inflation, crude oil, the rupee and global financial conditions.
Market expectations have increasingly factored in the possibility of a 25-basis-point rate hike, although a hawkish hold also remains possible if the RBI prefers to assess incoming data. In the near term, the direction of crude oil, US bond yields and foreign flows will remain critical. Atten-tion will also centre on FOMC minutes and a run of Fed speeches for further clarity on the cen-tral bank’s reaction to recent data.
The geopolitical crisis in the Middle East had entered its eighth month and resulted in severe dis-ruptions to global commodity supplies, with Brent crude staying above $100 a barrel. The persis-tent energy shock also stalled the multi-year global disinflation process, while higher diesel, jet fuel and natural gas prices put pressure on household savings and trade balances in energy-importing countries.
However, until oil prices and global yields moderate, the market is likely to remain sensitive to global cues and policy signals. Q2 earnings season, changing market conditions and shifting risks across global markets make it important for investors to stay agile with their portfolio and asset allocation.
FUTURES & OPTIONS / SECTOR WATCH
Sustained selling pressure continued during the monthly settlement week amid elevated crude oil prices and persistent global uncertainties. Nifty declined more than 3 per cent on a weekly basis while Bank Nifty outperformed with a relatively moderate decline of over 2 per cent. The Nifty traded in a wide 862.95-point range before some recovery emerged from the lows.
In the options segment, strong Call open interest for Nifty was observed at the 22,700 and 22,800 levels while major Put open interest was concentrated at the 22,300 and 22,000 levels. For Bank Nifty, significant Call open interest was seen at 55,000 level whereas notable Put open interest was also placed at the 54,000 level. Implied volatility (IV) for Nifty’s Call options settled at 12.49 per cent while Put options concluded at 13.87 per cent. The India VIX, a key indicator of market vola-tility concluded the week at 13.49 per cent.
The Put-Call Ratio Open Interest (PCR OI) stood at 1.04 for the week. Nifty rollovers declined to 74.29 per cent from 77.39 per cent last month and remained below the three-month average of 76.48 per cent indicating relatively weaker rollover activity. Bank Nifty future rollovers were broadly stable at 79.31 per cent compared to 79.19 per cent last month and remained above the three-month average of 77.55 per cent. However, the index is trading below its 55,700–55,800 rollover zone making 55,800 a key resistance level. Re-sistance to the Nifty is expected at 22,600 and 22,800, while supports are placed at 22,200 and 22,000.
The near- oversold technical setup makes aggressive fresh shorts susceptible to a sharp counter- trend rebound. With the RBI policy decision on October 7 adding an event-risk dimen-sion to an already fragile technical setup, volatility may remain elevated. The preferred ap-proach for the week ahead is to remain stock-specific, light on leverage and disciplined with risk, while allowing the Nifty’s behaviour around its 200-week MA to establish whether the anticipat-ed technical rebound can develop into a more meaningful recovery.
Stocks looking good are Enrin (Siemens Energy), Kotak Bank, HDFC Bank, Powerindia (Hitachi En-ergy), Mankind and Sona Comstar.. Stocks looking weak are Adani Energy, Godfrey Phillips, Tata Power, Torrent Pharma, Patanjali and Vedanta.
(The author is a senior maket analyst and former vice-chairman, Andhra Pradesh State Planning Board)
Usha Martin Limited
The company is a specialty steel wire rope solutions provider. It is also engaged in the manufac-turing of wires, low relaxation prestressed concrete steel strand (LRPC), wires, prestressing solu-tions, cables, and bespoke end-fitments and accessories. Its segments include Wire and Wire ropes, and others. The Wire and Wire ropes segment is engaged in the manufacturing and sale of steel wires, strands, wire ropes, cords, related accessories, wire drawing and allied machine, among others.
The others segment is engaged in the manufacturing and sale of jelly filled and optical fiber telecommunication cables. It provides various wire ropes, such as crane rope, min-ing rope, elevator rope, oil and offshore rope, fishing rope, general engineering rope, aerial transportation rope, structural rope, and conveyor rope. Its LRPC strands include unbonded pol-ymer coated LRPC strand, bonded polymer coated LRPC strand, compacted LRPC strand, and in-tended LRPC strand.
The share of wire ropes in revenue is 73 per cent, while the share of value-added products within wire ropes is 70 per cent. The revenue contribution of international mar-kets increased to 57 per cent. This richer product and geographic mix were one of the principal drivers of the improvement in margins and returns. Buy on declines for medium term target of Rs750.
CBI begins probe into Kaleshwaram project?
Kishan urges ryots to lead 'White Revolution 2.0'
Cops register case over Janhvi Kapoor AI video
Decriminalising GST regime augurs well
Justice must not only be done but also remain beyond doubt
A tale of two cities: Unmasking the reality of Hyderabad’s urban boom


