

- Rain and thunderstorms likely in South India
- Kalki Bhagavan Dies At 77: Spiritual Leader And Founder Of Oneness Movement Passes Away In Chennai
- Apple Pay arrives in India, Axis Bank named first partner
- One killed after tipper lorry collides scooter in Hyderabad
- Maharashtra Baby Trafficking Case: Couple Allegedly Sells Infant For Rs 1.2 Lakh, 7 Arrested
- Petrol and diesel prices today in Hyderabad, Delhi, Chennai and Mumbai on 30 September 2026
- Gold rates today in Hyderabad and Visakhapatnam surges, check the prices on 30 September, 2026
- Gold rates today in Bengaluru and Chennai surges, check the prices on 30 September 2026
Instant Personal Loan vs Regular Personal Loan: What's the Real Difference?
In Short
Understand the key differences between instant and regular personal loans, including approval time, eligibility, documentation, interest rates, repayment terms and processing fees to choose a suitable borrowing option.
Share :
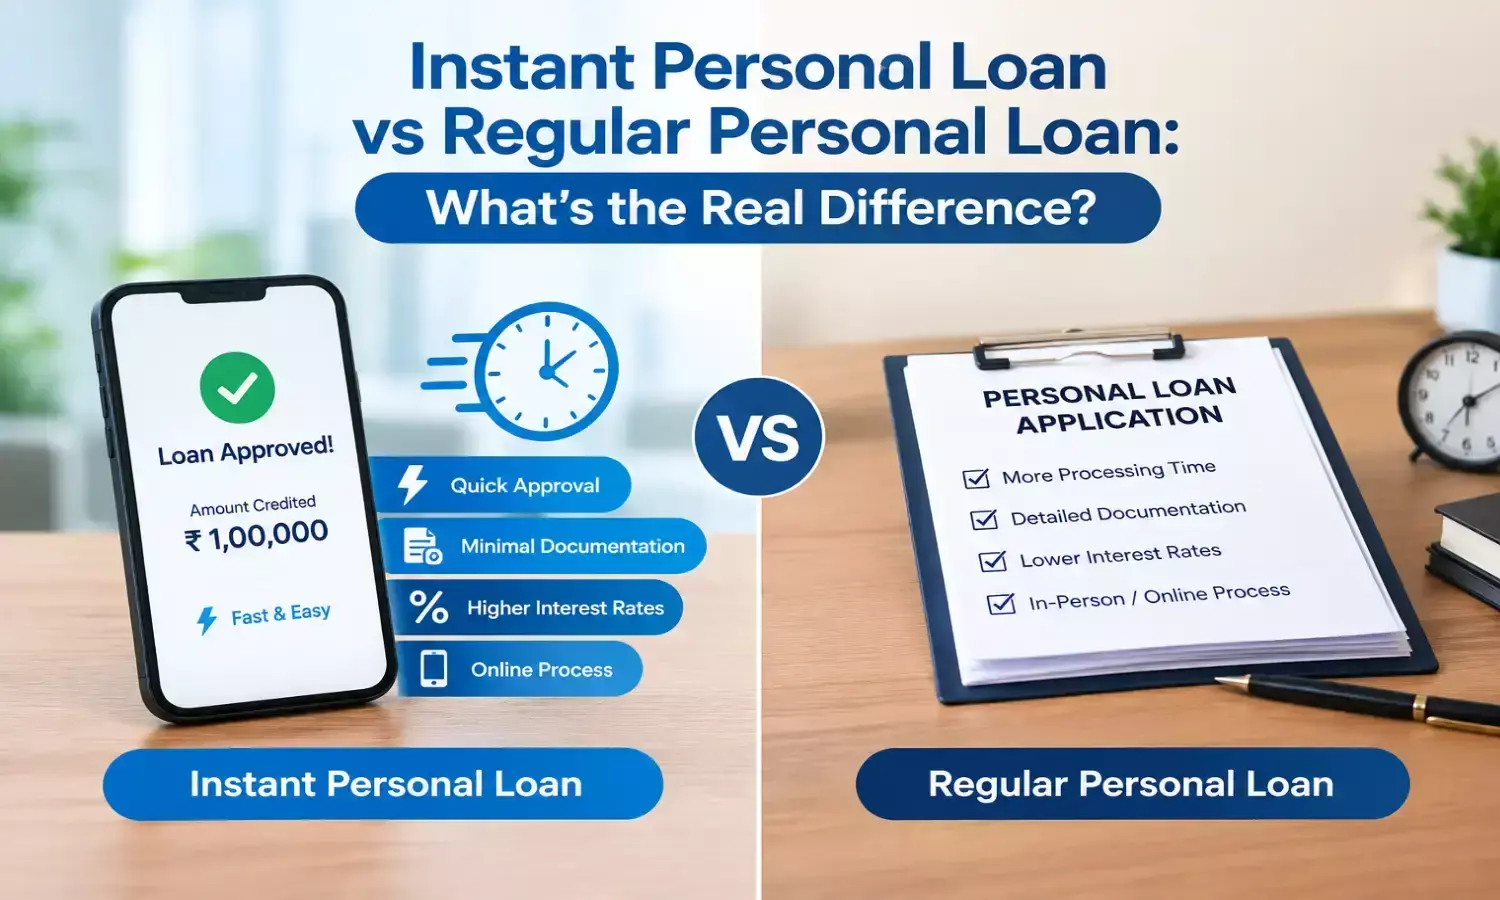
Instant Personal Loan vs Regular Personal Loan: What's the Real Difference?
Instant personal loan and regular personal loan are basically similar types of loans, where the only difference between the two is the process time taken. But before applying for a personal loan, ensure that you take into account some of the things such as the interest rates, APR, charges, duration of the loan, and repayment terms of your loan.
Quick Read
- An instant loan might prove to be an excellent choice for you if you require urgent funding and a completely online application procedure.
- Your salary, credit score, and EMIs currently running can have an effect on the amount of money that you can get in the form of the loan.
- Low EMIs will end up costing you more because you will have to pay high interest rates for your loan due to the increased tenure period.
- Before applying for the loan, make sure you know about KFS, APR, and other costs involved.
Money issues rarely come when you are prepared for them. One random expense can happen and leave an imprint on the upcoming month's budget, as a sudden need for extra cash becomes apparent. An easy solution would be a personal loan that can be acquired within mere minutes, but the process of getting one is not the sole consideration for the borrower. The interest, charges, and repayments matter just as much.
What Is an Instant Personal Loan?
An instant personal loan basically entails a faster process of applying for and verifying the loan online. You may have to apply for your loan online and sometimes upload your documents depending on the lending platform. It is vital to keep in mind that instant does not necessarily mean that the loan will be granted, disbursed, and made available in your account within minutes since the lender will still have to assess and verify your loan application.
For digital loans, according to the RBI rules and regulations, the APR (Annual Percentage Rate) of the loan must be disclosed by the lender along with other relevant standards for borrower's consent and privacy issues among others.
What Sets an Instant Personal Loan Apart From a Regular Personal Loan?
The main difference is usually the speed and level of digital processing. An instant personal loan generally uses a faster application and verification process, while processing times for regular personal loans vary by lender.
Factor | Instant Personal Loan | Regular Personal Loan |
Application | Usually online | Online or offline |
Processing | Generally faster | Varies by lender |
Verification | Often digital | Digital or manual |
Disbursal | Usually faster after approval | Depends on the lender |
Interest and fees | Vary by lender | Vary by lender |
Note: The faster process doesn't necessarily equal a lower-cost loan. Before taking out any loan, carefully consider the APR, the fees, and the various repayment options.
What Do You Need to Check Before Taking Out an Instant Personal Loan?
Before you take an instant personal loan, compare the speed of disbursement with the following factors:
- APR and the Interest Rate: Know what you will pay as a borrower and how the interest rate will affect your EMI.
- Processing Fees: Get informed about taxes and processing fees.
- Prepayment Terms: Get to know about the prepayment fees, if any.
- KFS: Key Facts Statement (KFS) gives you the critical details about your loan like its value, APR, fees and so on.
- Concerning the Lender: It is very important to check whether the digital lending app you have chosen is connected to a regulated bank or NBFC.
The RBI advises that, before applying for a digital loan, you should read the Key Facts Statement, the sanction letter, the privacy policy, and any other relevant documents carefully.
Conclusion
For borrowers who need quick access to funds, platforms like Finnable offer a digital personal loan application with a paperless process and no collateral requirement. Eligible applicants can borrow up to ₹10 lakh, with repayment tenures of 6 to 60 months and disbursal in as little as 60 minutes, subject to approval and verification.
Faster digital processes can help salaried professionals manage urgent personal expenses without a lengthy application process. However, the final loan amount, interest rate, fees, and repayment terms depend on the applicant’s eligibility and financial profile.


